What Is a Joint Venture Industry Model? A Plain Guide
A joint venture industry model is a way for two or more organisations to run a shared business activity under shared control, while each stays independent. The activity might be a new product, a training programme, an annual conference or a market entry. The partners agree what each contributes, who decides what, and how the rewards, risks and eventual exit are handled. Different industries add their own twist. In membership bodies, charities and education, the usual pattern is that one party keeps control of the mission and the members, while the other supplies capital, marketing or technology.
This guide explains the definition, the structures a JV can take, whether it must be 50/50, and how associations and nonprofits use the model in practice.
TL;DR
- A joint venture is an arrangement where two or more parties carry out an economic activity under joint control. Unanimous consent on key decisions is the test.
- It does not have to be a new company. A JV can be purely contractual, a shared set of assets, or a separate entity.
- Ownership can be any split, such as 50:50, 60:40 or 70:30. Control is a separate question from ownership.
- Many JVs are built for a defined project and are designed to end or mature, not to last for ever.
- A written agreement on governance, contributions and disputes matters more than any other single factor.
Table of Contents
- What a joint venture industry model actually means
- The test that defines a joint venture: joint control
- Three forms a joint venture can take
- Is a joint venture always 50/50?
- How the model works in membership bodies, charities and education
- Time-bound by design
- Advantages and risks
- What a good joint venture agreement covers
- A step-by-step way to test the idea
- Our perspective: start with the shared data, not the shared logo
- Where Colossus fits
- FAQ
- Sources
What a joint venture industry model actually means
The phrase “joint venture industry model” is not a formal legal term. People use it to mean the standard way joint ventures are set up and run in a given sector: who typically partners with whom, how the split of work and money usually looks, and what the arrangement is for.
The underlying definition is well established. Under the accounting guidance for smaller companies, a joint venture is a contractual arrangement in which two or more parties undertake an economic activity subject to joint control. Note the wording: an economic activity, not an entity. That is why a JV can exist without a new company being formed.
Three features separate a genuine JV from other relationships:
- Shared contribution. Each party puts in money, people, assets, data, brand or expertise.
- Shared control. Important decisions need all the controlling parties to agree.
- Shared outcome. Profits, losses and risks are divided according to the agreement.
If one party can make every decision alone, you do not have a joint venture. You have a subsidiary or a service contract.
The test that defines a joint venture: joint control
The defining question is not who owns the most. It is who can decide. The IFRS guidance explains that joint control requires unanimous consent on the relevant activities, the decisions that most affect the venture’s returns, such as budgets, pricing, hiring and strategy.
This has practical consequences:
- A 51% owner who can outvote the other side on everything has control, not joint control.
- A 50% partner with a veto over the budget and strategy may have joint control even with a minority holding.
- Where decisions are made by simple majority and one party always holds it, the label “joint venture” is a courtesy rather than a description.
Both sides therefore stay accountable. A JV is not a way of handing a risk to someone else. Shared governance means shared responsibility for success and for failure.
Three forms a joint venture can take
The IFRS for SMEs module describes three forms of joint arrangement, and they are a useful map for any sector.
| Form | What it means | Separate entity? | Example |
|---|---|---|---|
| Jointly controlled operations | Each party uses its own assets and staff for a shared activity | No | An association supplies the speakers and members, a partner supplies the filming crew and platform, and revenue is shared by contract |
| Jointly controlled assets | The parties jointly own assets dedicated to the venture | Not necessarily | A co-owned course library or event database |
| Jointly controlled entity | A separate business is created and run by the parties | Yes | A company or LLP set up to run a certification programme |
The PwC UK GAAP manual makes the same point: the accounting and liability treatment differs between these forms, so it matters which one you are in.
Legal vehicles in the UK
In England and Wales, the entity route usually means one of the following. UK solicitors describe the main options as a special purpose limited company, a partnership or LLP, or a contractual collaboration agreement with no new vehicle. Each has different tax and liability consequences. An LLP is taxed on a transparent basis, so each party is taxed on its own share of profits, while a limited company is a separate taxpayer. A JV can also be set up as a corporate, contractual or partnership arrangement, and in some cases a general partnership under the Partnership Act 1890 can arise by accident if you behave like partners without a proper agreement. Take advice from a solicitor and an accountant before you choose, because the choice is hard to reverse.
Is a joint venture always 50/50?
No. Many are split evenly, but any ownership split is possible, including 60:40 and 70:30. The split should reflect contributions and risk, and it should be separated from control. A common compromise in sectors where one party carries a mission or regulatory duty is a majority stake for that party, plus reserved matters: a list of decisions that need the minority partner’s consent.
In the membership and education world, a 51/49 structure or a revenue-sharing agreement is a familiar pattern. The institution keeps oversight of what it is accountable for, and the partner brings the capital, marketing and infrastructure. Reporting on higher education partnerships in Inside Higher Ed describes this type of arrangement between colleges and outside partners. Be aware that a strict 51/49 split with the majority party deciding everything may be a service arrangement in legal terms, not a JV.
How the model works in membership bodies, charities and education
In this sector the model has a recognisable shape: a clear division of labour.
- The organisation keeps the core. In higher education that means hiring faculty, awarding qualifications and admitting students. For an association it means standards, member relationships, codes of conduct and the credential itself.
- The venture handles the services. Marketing, learner or member support, finance and technology platforms sit in the shared activity.
The EDUCAUSE chapter on nonprofit and for-profit partnerships traces how these structures grew out of long-standing collaborations between institutions. Often a need comes first, such as a gap in provision, and the partnership then develops around it.
This separation limits risk while letting a professional programme scale faster than the organisation could alone.
Realistic examples
These are illustrative patterns, not named case studies:
- A professional body and a training company create a certification programme. The body owns the standard and exam. The partner runs delivery, marketing and virtual classrooms. Revenue is shared.
- Two associations in adjacent fields co-host an annual conference. Each brings its membership list, they share sponsorship income and costs, and the event ends or is renewed after three editions.
- A charity and a corporate partner run a fundraising series. The charity keeps donor relationships and compliance. The partner funds production and promotion.
- A community programme with a cohort model. Organisations that build leadership or professional development programmes for specific communities, such as the cohort-based leadership programme from RELA for professionals in the African diaspora, show the kind of focused, selective offer that a membership body might develop with a delivery partner rather than build alone.
Time-bound by design
A common misconception is that a JV is a permanent business. UK government guidance for public bodies forming joint ventures with the private sector sets out the factors to weigh before deciding a JV is the right delivery route, and it treats the exit as part of the design. Many successful ventures are built around a specific goal, such as launching a certification or scaling an annual event, and then dissolve, convert to a different arrangement or are bought out.
So define the finish line before you start. Ask:
- What will count as success, and by when?
- What happens to the data, content and intellectual property at the end?
- Can one party buy the other out, and at what valuation method?
Advantages and risks
Why organisations choose the model
- Speed. You borrow capacity you would take years to build.
- Shared cost and risk. Capital outlay is split, so a failed launch hurts less.
- Access. A partner may bring audiences, technology or accreditation you lack.
- Focus. Your staff keep running the core membership while the venture handles the new line.
What goes wrong
- Mission drift. The partner’s commercial goals pull the programme away from your purpose.
- Unclear control. Disagreements over pricing or content stall the venture.
- Hidden liability. Because control is shared, both parties remain accountable.
- Data and member trust. Sharing member data without a lawful basis and clear consent can breach data protection law. Take advice from a data protection specialist before any list or CRM data moves between partners.
- No exit. Without agreed exit terms, a dispute can trap both sides.
What a good joint venture agreement covers
Practitioners agree that formalising the arrangement is the most important factor in long-term success. The EDUCAUSE chapter notes that partnerships often start as simple support contracts, for example outsourcing one tool, and grow into joint ventures as trust and revenue grow. At that point the paperwork has to keep up. A sound agreement usually covers:
- Purpose and scope. What the venture does and does not do.
- Contributions. Cash, staff, assets, brand and data from each side, and any transfer of intellectual property.
- Governance. Who sits on the board or steering group, quorum, and reserved matters that need unanimity.
- Money. How profits, losses, fees and reinvestment are handled.
- Deadlock. What happens when the parties cannot agree.
- Disputes. Mediation or arbitration before litigation.
- Exit. Term, buy-out rights, wind-up and what each party keeps.
The International Chamber of Commerce publishes a model joint venture contract aimed at balanced terms for cross-border and domestic cooperation, which is a useful reference point for your solicitor’s draft. Solicitors consistently advise seeking legal advice and putting an agreement in place whichever structure you pick.
A step-by-step way to test the idea
- Write the objective in one sentence. If you cannot, the venture is not ready.
- List what you each bring. Be honest about gaps.
- Try a smaller contract first. Pilot a single tool, event or course with a service agreement. Move to a JV only if trust and revenue justify it.
- Agree the control model. Decide which decisions are reserved for unanimity.
- Take professional advice. A solicitor for the agreement, an accountant for tax and reporting treatment.
- Set review dates. Check performance at 6 and 12 months and decide whether to continue, restructure or end.
Our own guides on building partnerships to grow a membership organisation and community partnerships for member engagement cover the earlier, lighter stages of this path.
Our perspective: start with the shared data, not the shared logo
We work with membership organisations, associations, nonprofits and educational institutions, and the partnerships that cause trouble are rarely the ones with a weak idea. They are the ones where nobody can see the same numbers. One side holds the member records, the other holds the event registrations and the payment data, and every report becomes a negotiation.
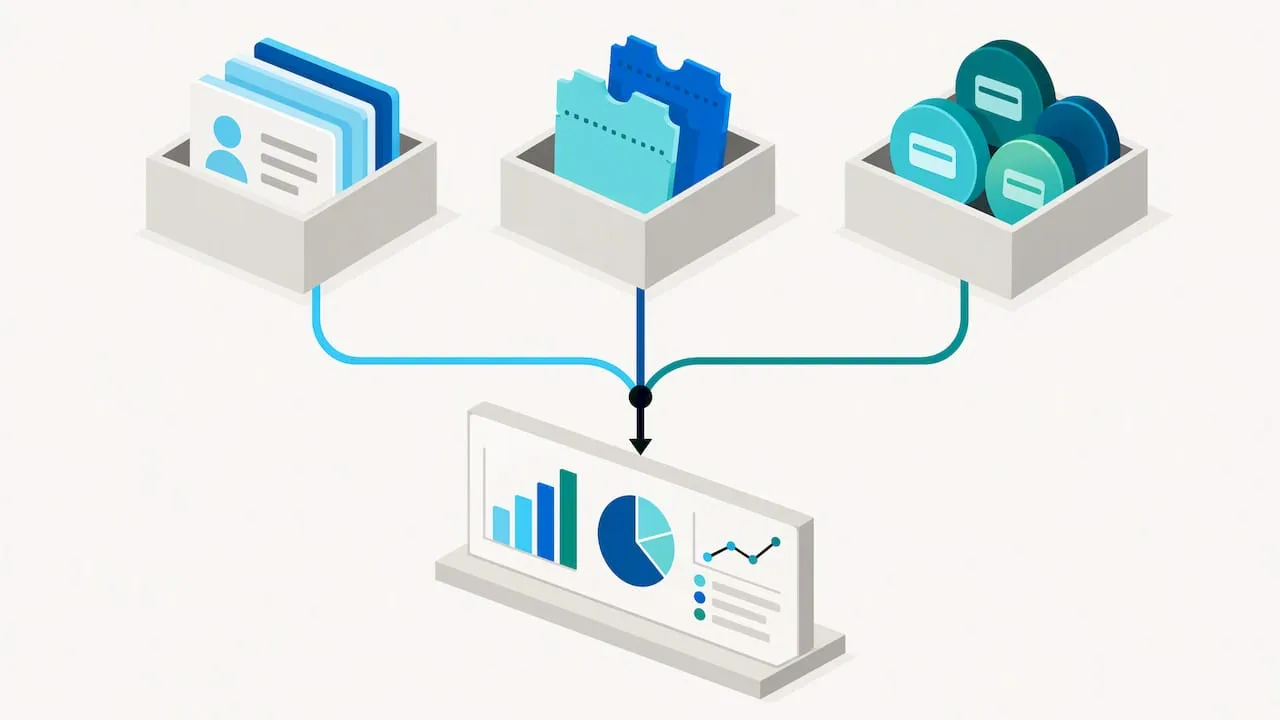
Our view is that a venture works best when both parties operate from a single source of truth: one member database, one event calendar, one set of payment records and one analytics view. That is the reason we built Colossus as an all-in-one platform rather than a stack of separate tools. When membership, events, CRM, email and e-commerce live together, it is far easier to show a partner exactly what a programme earned, who attended and which members are engaged, and far easier to set permissions so that each side sees only what the agreement allows.
We would add three points of advice. First, keep member ownership with the organisation unless there is a strong reason not to, because trust is your most valuable asset. Second, decide the reporting format in the agreement, so no one argues about numbers later. Third, treat the partner’s technology as replaceable: if you leave, your records and content should leave with you.
— Rob
Where Colossus fits
If you are planning a co-run programme, a shared event series or a new certification, you will need a place to manage members, registrations, payments and reporting that both sides can rely on. Our membership management software and event management software bring these together, with a CRM for tracking relationships. Plans start with Core at £349 per month, with Growth at £699 per month, Scale at £1,299 per month and Enterprise from £2,500 per month. A contributor licence is available from £29 per month. See the full pricing page for what each plan includes.
If events are the heart of your venture, our guides to virtual charity events and online event promotion are good next reads.
FAQ
What is a joint venture model in simple terms?
It is an arrangement where two or more organisations team up on a specific business activity and share the control, costs and rewards. Each stays a separate organisation. They agree the terms in a contract, and sometimes form a new company or LLP to run the activity.
What are the main types of joint venture?
The accounting guidance describes three forms: jointly controlled operations, jointly controlled assets and jointly controlled entities. In UK practice the legal vehicle is usually a limited company, a partnership or LLP, or a contract-only collaboration.
Does a joint venture need a new company?
No. A JV can be purely contractual, with the parties using their existing assets and staff and sharing control under an agreement. A separate entity is one option, chosen for liability, tax and governance reasons.
Is a joint venture the same as a partnership?
Not quite. A partnership under the Partnership Act 1890 is a legal relationship in which partners operate a business together and share liability unless the agreement says otherwise. A JV is a broader idea that may or may not use a partnership as its vehicle. Ask a solicitor which applies to your plan.
How long does a joint venture last?
It lasts as long as the agreement says. Many are created for a defined project and end when the goal is met, while others convert into a permanent business or a buy-out.
Sources
- IFRS for SMEs Educational Module 15: Joint Arrangements
- PwC: Scope, definitions and forms of joint ventures
- Inside Higher Ed: Joint Ventures, Pre-Distress
- EDUCAUSE: Nonprofit/For-Profit Academic Partnerships in Higher Education
- UK Government: Joint Ventures guidance
- Optimal Solicitors: Joint ventures
- Go Legal: Joint Venture Agreement UK
- ICC Model Contract: Joint Venture